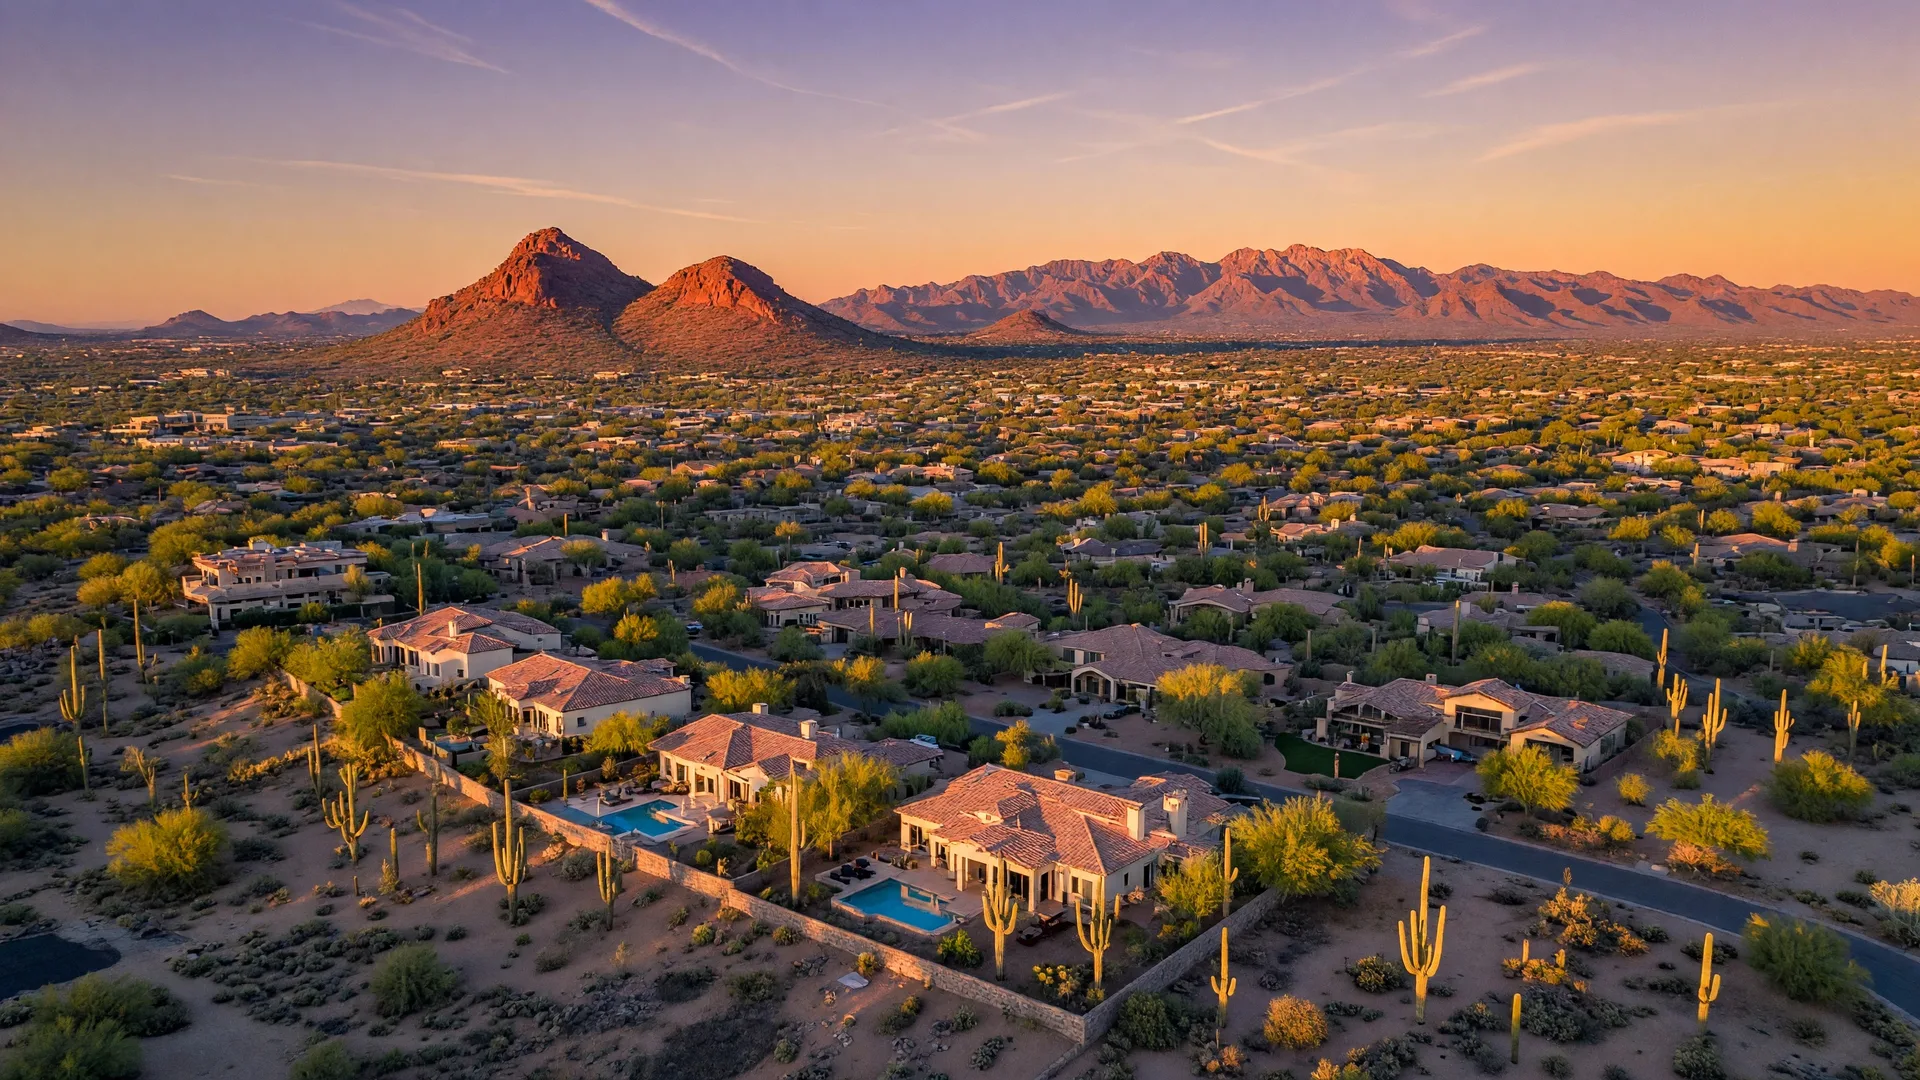
A luxury villa is not just a bigger house, it is built with different materials, finished to a different standard, and would cost far more to put back together after a loss. That is why standard homeowners insurance, designed for tract homes, almost never fits a custom or high-end property. This guide walks through the coverage basics villa owners should understand: true rebuild cost, personal property limits, liability protection, umbrella policies, and scheduled valuables.
Insure the rebuild, not the sale price
The single most important idea in luxury insurance is that you insure what it would cost to rebuild the home, not what it would sell for. Market value includes land, location, and demand, none of which you need to replace after a fire or storm. Rebuild cost reflects what a contractor would charge today to reconstruct the structure with comparable materials: imported stone, custom millwork, designer kitchen cabinetry, specialty plaster, and high-end systems.
For a custom villa, those costs can be materially higher than for a comparable-size standard home, and coverage that is even modestly short can leave an owner paying the gap out of pocket. A knowledgeable high-value insurer will run a detailed replacement cost valuation on your home, often including your floor plans and an inspection, and the policy limit should be reviewed whenever you renovate or finish an addition.
Personal property: know your limits
Standard policies cover your belongings, but usually up to a cap, often calculated as a percentage of the dwelling coverage. Fine jewelry, watches, art, antiques, furs, musical instruments, and collectibles routinely exceed those caps. The fix is a scheduled personal property rider, an endorsement that lists each valuable item individually with an agreed value based on a current appraisal. When the coverage is scheduled that way, a claim is settled on the agreed amount rather than on a fight over what the piece was worth.
If your villa is furnished with large art pieces, wine storage, or designer wardrobes, inventory it with photos and appraisals, and revisit the schedule when you acquire or sell pieces. High-value policies may also cover fine art transit, restoration, and loss of value in ways standard policies will not.
Liability, guests, and umbrella protection
A villa often means more liability exposure: pools and spas, entertaining guests, staff, and a larger property for visitors to explore. Base liability limits on a homeowners policy may not feel adequate for that scale of risk. Raising limits on the home policy itself helps, but the most efficient layer is an umbrella or excess liability policy that sits on top of your home, auto, and other coverage and provides a much higher limit for claims that exhaust the underlying policies.
Umbrella coverage is typically relatively affordable for the protection it adds, and high-value insurers frequently require it as part of the package. It is also worth asking how your policy handles incidents involving household staff, pet owners' liability, and pool accidents, because those are the claims luxury homeowners actually encounter.
Other structures and specialty features
Most policies include some coverage for other structures on the property, but a separate guesthouse, casita, pool house, workshop, or stable may need to be scheduled at its own replacement value. Specialty features common on villas, pools and spas, outdoor kitchens, wine cellars, generators, solar arrays, and advanced smart-home and security systems, each come with their own coverage questions, and policy language varies widely on how they are valued after a loss.
Arizona realities to talk through
In Metro Phoenix and the high-desert communities nearby, a few local realities deserve attention: intense sun and heat shorten the useful life of roofs and air conditioning systems, monsoon winds can damage tile and stucco, hard water affects plumbing and fixtures, and foothills properties can face wildfire exposure. None of this changes the advice to insure for full replacement cost, but it should shape the condition and carry-over of coverage you ask about, and how your provider handles aging roofs and systems when you file a claim.
Why an experienced high-value insurer matters
The strongest reason to work with a specialist high-value home insurer is the claim experience. These carriers assign dedicated adjusters who understand custom construction, they offer agreed-value options for many items, and they routinely handle the kinds of losses large estates face. A generalist policy written to save money can be the expensive choice when a villa is seriously damaged. Get quotes from high-value specialists, compare the wording, not just the price, and have an insurance professional you trust review the package with your villa's actual features in mind.
I am not an insurance agent, and this is general guidance, not a policy recommendation. For your specific villa, talk with a licensed insurance professional who works with high-value homes in Arizona. And when you are buying or selling a luxury property in the Valley, I am glad to help you line up the right professionals and the right questions to ask. Reach me at 480-980-4400 or schedule a consultation.
Denise Hurd
Luxury Real Estate Specialist · RE/MAX Premier
With more than 30 years of experience working with Arizona homeowners, I can connect you with trusted local counsel and answer your real estate questions. Call me at 480-980-4400 or schedule a consultation.